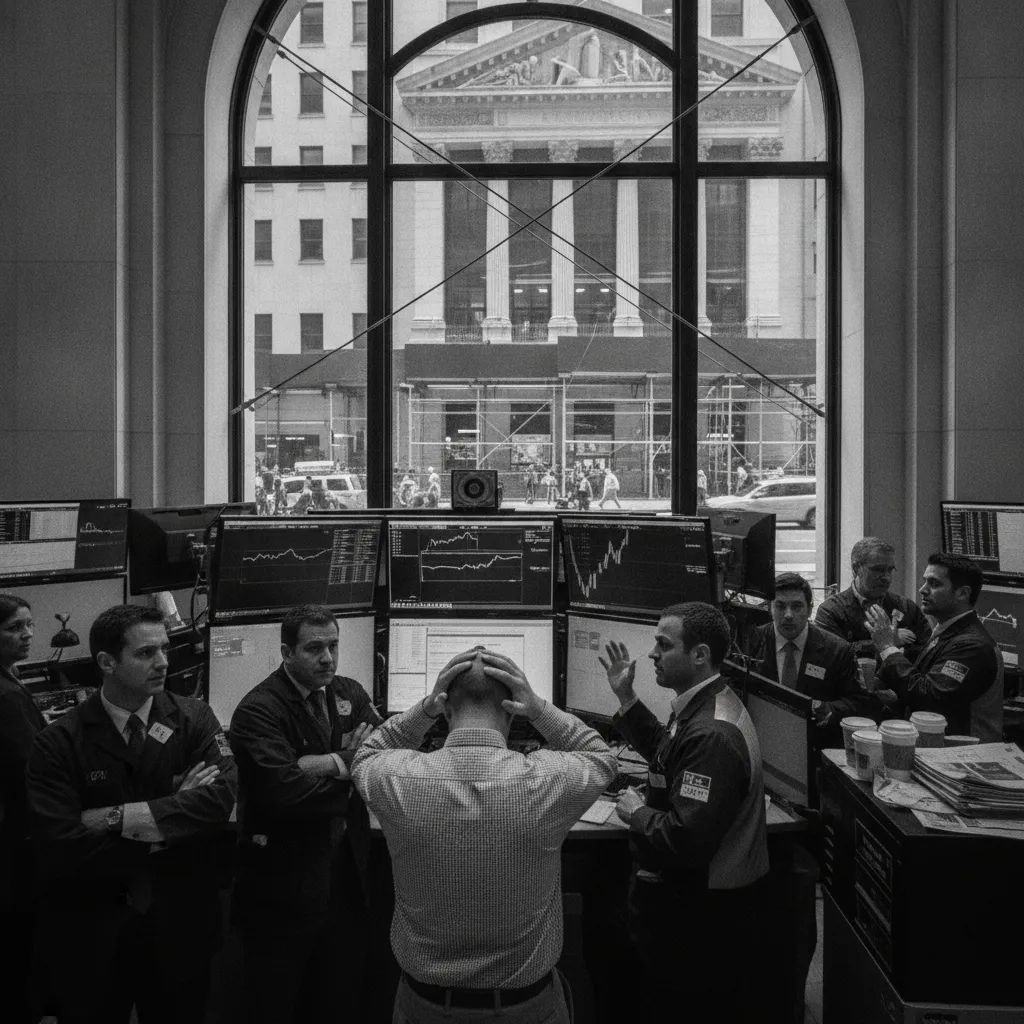
Wall Street recently marked four years of a relentless bull market, fueled largely by a massive infrastructure build out for artificial intelligence. While many analysts spend their days debating whether AI valuations have stretched too far into bubble territory, some seasoned observers argue that there is a much more dangerous threat lurking beneath the surface of the indices. History suggests that while transformative technology eventually pays off, the initial excitement often leads to reckless behavior that ends in a crash.
The real concern isn’t necessarily the software or the chips, but rather how investors are paying for them. Outstanding margin debt, which refers to money borrowed from brokers to leverage bets on securities, has reached staggering heights. By hitting a peak of over 1.5 trillion dollars earlier this year, these figures signal an appetite for risk that borders on the extreme. Leverage can certainly amplify gains during a climb, but it acts as an accelerant for losses once the tide turns.
Looking back at market cycles since 1998, there is a chilling pattern associated with parabolic spikes in borrowing. On three separate occasions leading up to the dot com collapse, the 2008 financial crisis, and the post pandemic correction, margin debt surged by at least 65 percent over a short window before everything broke. Each of those episodes was followed by devastating declines in both the S&P 500 and the Nasdaq as panicked investors were forced to sell assets to cover their loans.
Current data indicates we are repeating this cycle with alarming precision. Between April 2025 and June 2026, margin debt skyrocketed by 77 percent in just fourteen months. With markets already trading at premium prices driven by AI optimism, any sudden shift in sentiment could trigger a cascade of forced liquidations. If investors decide they have finally pushed their wagers too far, it may not take much more than a slight tremor to send equities tumbling toward a painful correction.