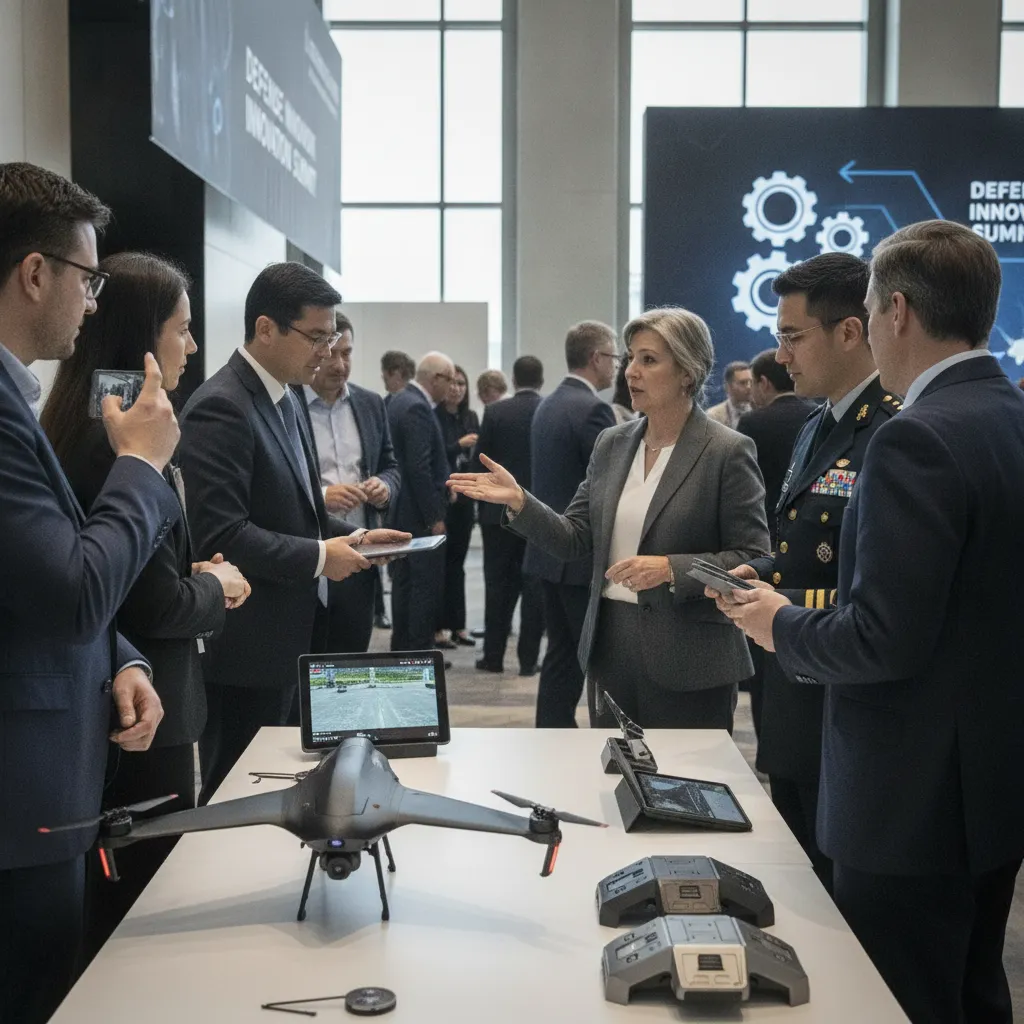
A massive wave of private equity is flooding into the defense technology sector, transforming how military innovation is funded. Driven by escalating geopolitical tensions and a global rush to modernize arsenals, investment has skyrocketed. According to data from PitchBook, private equity growth investments in defense hit four billion dollars in the first nine months of 2026, a staggering leap from just five hundred million dollars in 2024. This shift marks a departure from previous years when many investors were either restricted or simply reluctant to enter the politically sensitive world of arms and security.
The funding landscape is shifting as the line between venture capital and private equity blurs. While venture capital typically fuels early startups, private equity firms are increasingly stepping in earlier to bridge the gap between an initial invention and industrial scale production. From autonomous drones to satellite systems, these firms provide the heavy lifting required for companies to expand their manufacturing capabilities. A survey conducted by White and Case highlights this desperation for capital, with nearly all senior decision makers at UK defense firms expecting to seek significant external funding within the next year.
However, this gold rush has triggered warnings about a potential financial bubble. Some industry veterans argue that valuations have become detached from reality, with companies being priced based on technological promise rather than actual revenue or order books. Shonnel Malani of Advent International noted that there is considerable froth in the system, admitting his firm has walked away from deals where prices had become silly. He warns that a market correction may be inevitable if these high flying startups fail to turn their prototypes into commercial successes.
Not everyone shares this pessimism, however. Some analysts believe that growing national budgets and the urgent need to replenish ammunition stocks create a stable foundation for long term bets. Meanwhile, traditional buyout firms continue to focus on profitable, established suppliers that need capital specifically for scaling production capacity rather than speculative research. As Europe looks to consolidate its fragmented supply chain, the influx of cash remains critical, even as observers wonder if the current valuation surge can be sustained over time.